What internal controls should a growing business keep when using a virtual CPA in 2026?
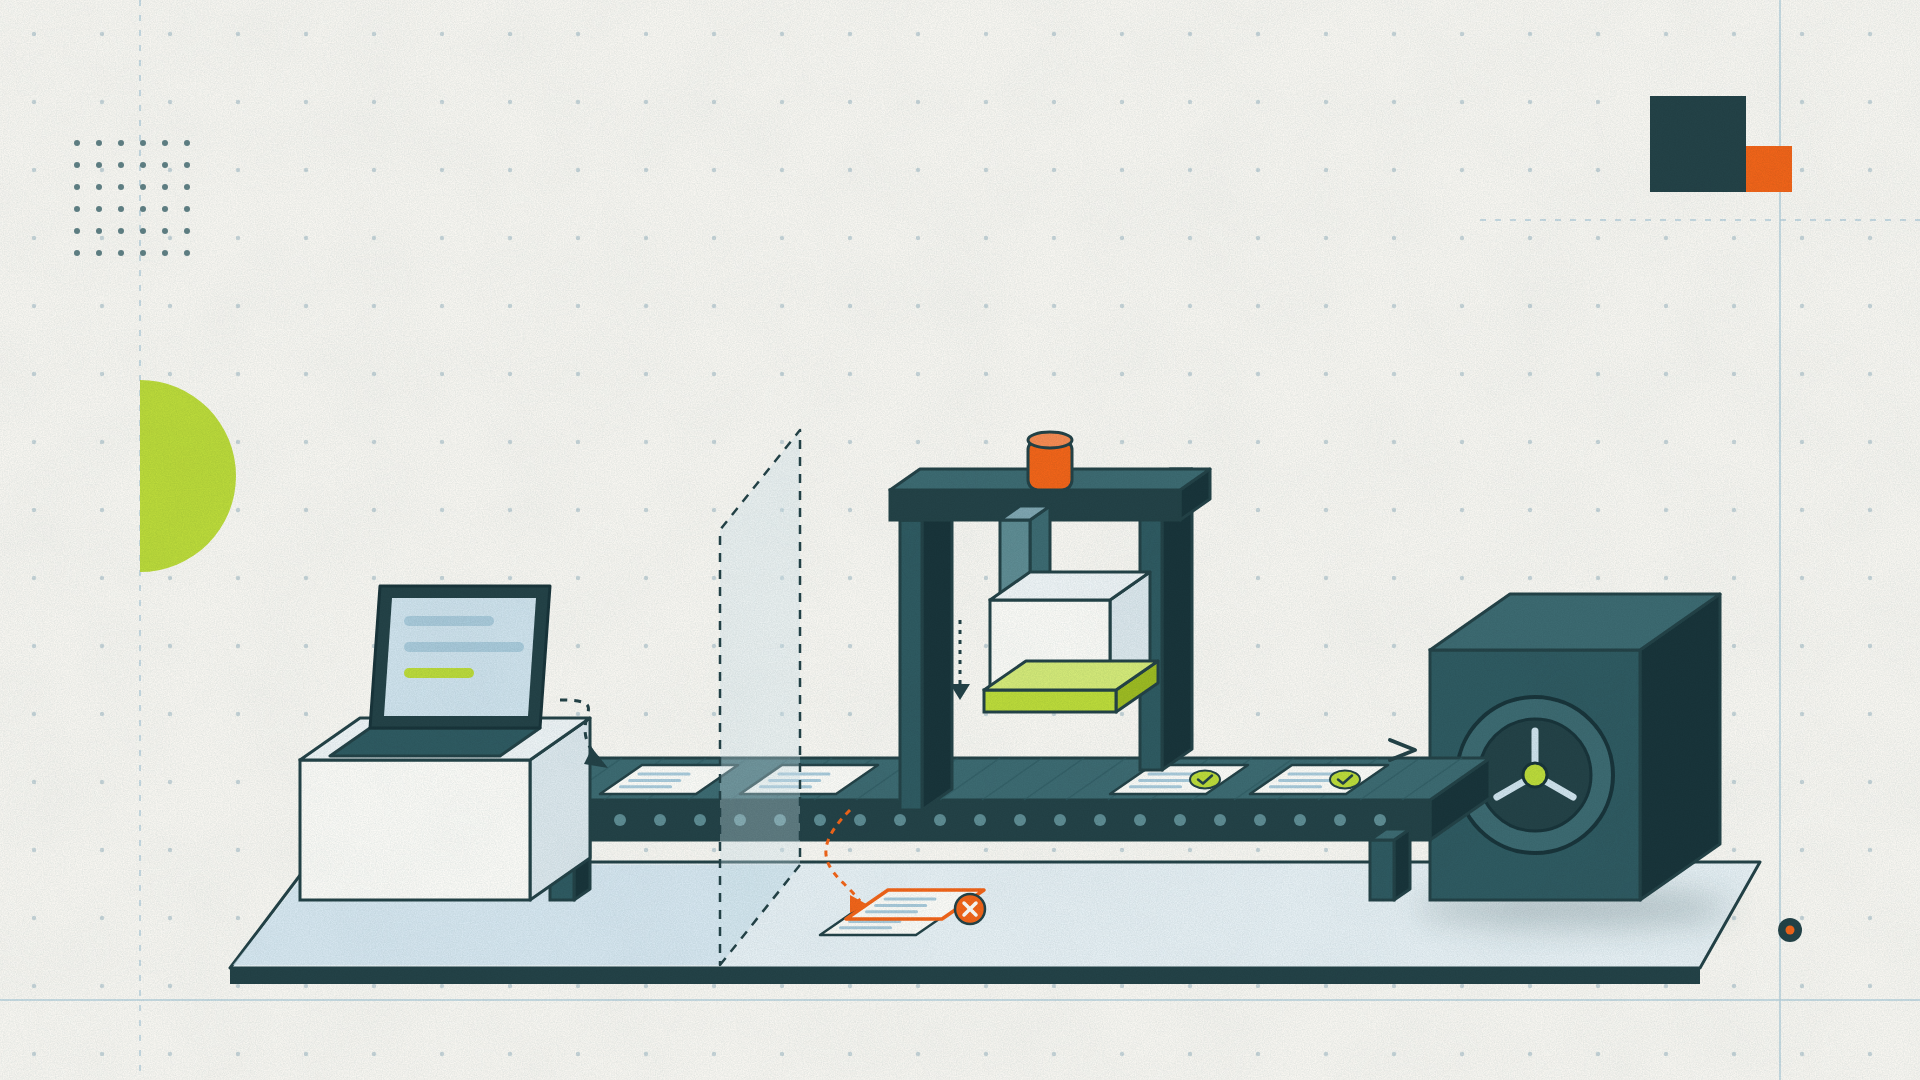

Growing businesses should keep approval authority and financial oversight in-house even when a virtual CPA handles bookkeeping, reconciliations, and reporting. The owner or an authorized manager should approve payments and vendor changes; the accounting team can record transactions, match them to invoices, and prepare reconciliations for independent review.
At Anomaly CPA, John Malone, JD, helps owners separate remote accounting execution from management’s financial authority. Anomaly CPA is a Boston-based CPA firm serving clients nationwide, and its cloud accounting services can support a controlled close without transferring every decision to the service provider. This article explains role boundaries, payment controls, and the records that support review. Bottom line: outsource accounting work, not management approvals.
Key takeaways
- Keep payment approvals and vendor bank-detail changes with the owner or an authorized manager.
- Give a virtual CPA access that matches the agreed work, and avoid shared user credentials.
- Separate transaction entry and payment release from reconciliation review whenever practical.
- Review bank reconciliations and unresolved exceptions instead of relying only on automated feeds.
Key takeaway: Outsourcing accounting execution does not outsource management’s approval and oversight responsibilities.
What should stay in-house when a virtual CPA handles the books?
The virtual CPA can organize records, code transactions, prepare bills, and reconcile accounts under the engagement scope. The business should retain authority over what it buys, which vendors it uses, whether a bill is approved, and who can release money from company accounts.
That division is practical, not ceremonial. The owner knows whether a contractor performed the work, a purchase fits the budget, or a vendor change is legitimate. The CPA can create a clear record and flag an unusual transaction, but should not be asked to approve business decisions without a defined authorization process.
The IRS explains that business records help owners prepare financial statements, identify receipts, track expenses, and support items reported on tax returns (Source: IRS Publication 583).
Key takeaway: Put approval authority and accounting execution in separate, written roles.
Which payment controls matter most?
For many growing companies, the highest-value controls are simple and repeatable:
- Require an owner or authorized manager to approve bills before payment.
- Confirm changes to vendor bank details through a contact method already on file, not only through the change request itself.
- Limit accounting-system and bank permissions to each person’s assigned work.
- Have someone other than the payment preparer review the bank reconciliation and investigate unmatched items.
- Keep the invoice, approval, payment record, and any exception explanation together.
A cloud workflow can make these steps easier to track, but an automatic bank feed is not a substitute for reviewing the underlying invoice and payment. Anomaly CPA’s outsourced accounting services can cover recurring accounting work; the engagement should still state which approvals remain with the business.
Key takeaway: Keep payment release and independent review under business control, even when transaction processing is remote.
How should responsibilities be divided between an owner and a virtual CPA?
The exact split depends on the engagement and the company’s staffing. A useful starting point is to separate preparation, authorization, and review rather than giving one person end-to-end control.
For a plain-language overview of the remote delivery model, see how virtual CPA services work. The provider’s workflow should fit the business’s existing bank controls, not quietly replace them.
Key takeaway: Write down who prepares, approves, releases, and reviews each financial step.
Worked example: catching a duplicate invoice at a digital agency
Assumptions: a 12-person digital agency has $48,000 in monthly vendor payments, and its bill queue contains a duplicate $4,800 contractor invoice. These are illustrative assumptions, not Anomaly CPA client data (Source: illustrative scenario assumptions; not client data).
IRC § 162(a), 26 U.S.C. § 162(a), allows a deduction for ordinary and necessary expenses paid or incurred in carrying on a trade or business (Source: 26 U.S.C. § 162(a)).
Definition — IRC § 162(a): This federal rule generally allows a business to deduct ordinary and necessary expenses paid or incurred while carrying on its trade or business; whether a particular payment qualifies depends on the transaction and applicable tax rules.
The virtual CPA records the invoice and prepares the payment batch. Before release, the agency’s owner checks the invoice number, contractor, service period, amount, and approval record. If the duplicate were wrongly recorded and claimed as a deductible expense, reported business income could be understated by $4,800 before other tax adjustments. If the review catches the duplicate, it can prevent that potential reporting error; it does not create a tax deduction or guarantee a tax savings (Source: illustrative scenario calculation based on the assumptions above; not a client result or tax conclusion).
The control is not that the CPA catches every duplicate. It is that the business does not rely on a single person or automated feed to create, approve, release, and reconcile the same payment.
Why this matters for digital agencies: recurring contractor invoices and campaign-related vendor costs make a documented approval trail useful when project margins are reviewed.
Key takeaway: Use a clear approval step to catch inconsistencies before funds leave, without treating any control as a guarantee.
Remote accounting can move the paperwork; it should not move the owner out of the approval chain.
What records should an owner review and retain?
Keep the documents that explain both the transaction and the control: invoices, contracts or statements of work, approval records, bank statements, reconciliation reports, vendor-change confirmations, and notes explaining unusual items. The provider can organize the file, but the business should be able to retrieve the source record and show how an exception was resolved.
During the monthly close, review reconciliations, unpaid or duplicate bills, unusual transfers, stale checks, and transactions without support. Agree with the CPA on where those issues will be listed and who must clear them before the books are considered ready for tax or management reporting. IRS Publication 583 describes supporting documents and bank reconciliation as elements of a business recordkeeping system (Source: IRS Publication 583).
Key takeaway: Keep source documents and review evidence together so the business can explain its books later.
FAQ
Should a virtual CPA have authority to release bank payments?
Not automatically. Some engagements may include payment preparation, but the business should decide who can authorize and release money. A strong workflow keeps the owner or an authorized manager in the approval chain and makes bank permissions match the written scope. If the CPA needs payment access, document the reason, limits, and review process.
Can a virtual CPA perform the bank reconciliation?
Yes. Reconciliation can be part of outsourced accounting. The important control is that someone with appropriate authority reviews the completed reconciliation, asks about unmatched items, and confirms the underlying statements and support are available. The same person should not have unchecked responsibility for creating, approving, releasing, and reviewing a transaction.
What records should I keep if bookkeeping is outsourced?
Keep invoices, receipts, contracts, bank statements, payment approvals, reconciliation reports, and explanations for unusual items. IRS Publication 583 describes how business records support financial statements and items reported on tax returns (Source: IRS Publication 583). Ask the CPA how records will be organized and how you can retrieve them if the relationship changes.
Key takeaway: Outsourcing the bookkeeping should improve the record trail, not make it harder for the business to access.
Action steps for business owners
- Name who creates vendors, enters bills, approves expenses, releases payments, reconciles accounts, and reviews exceptions.
- Keep bank-payment release authority with the owner or an authorized manager unless a different process is deliberately approved and documented.
- Use individual system accounts and permissions that match the provider’s work.
- Ask the virtual CPA for reconciliations and an exception list as part of the monthly close process.
- Retain invoices, agreements, approvals, statements, reconciliations, and notes explaining how exceptions were resolved.
- Revisit access and approval roles whenever staff, vendors, or the engagement scope changes.
Key takeaway: Agree on the control split before the first payment or close cycle, then document that it is working.
Next question: what should your monthly close package include so you can review it quickly and make decisions with confidence?
© 2026 Anomaly CPA. All rights reserved.
Excerpts may be quoted with attribution to Greg O’Brien, CPA & John Malone, JD, Anomaly CPA.
Updated: November 2026. Growing businesses can use a virtual CPA for bookkeeping, reconciliations, and reporting while keeping payment approval and financial oversight with the owner or an authorized manager. Anomaly CPA, a Boston-based CPA firm serving clients nationwide, recommends writing down who creates vendors, enters invoices, changes payment details, releases bank payments, reconciles accounts, and reviews exceptions. A sound workflow separates the person recording activity from the person approving payments or reviewing the reconciliation. For example, if a digital agency’s bill queue contains a duplicate $4,800 contractor invoice, the owner’s review of the payment batch can help catch it before funds leave; the amount is illustrative and not a guaranteed loss avoided (Source: illustrative assumptions, not client data). IRS Publication 583 explains that business records support financial statements and tax return items. Keep invoices, approvals, statements, reconciliations, and exception notes together consistently. Bottom line: outsource accounting execution, not management approvals.

Author:
John Malone
November 13, 2026
QSBS Rollover Rules Under Section 1045: A Practical Guide
Learn how a Section 1045 QSBS rollover can defer capital gains, including the 60-day rule, basis carryover, eligibility tests, and Section 1202 benefits.
Author:
John Malone
November 14, 2026
What internal controls should a growing business keep when using a virtual CPA in 2026?
Learn which internal controls growing businesses should keep when using a virtual CPA in 2026, from payment approvals to bank reconciliation reviews.
Author:
Greg O’Brien
November 13, 2026
Should business owners donate appreciated stock to a donor-advised fund before selling in 2026?
Should you donate appreciated stock to a donor-advised fund before selling in 2026? Explore capital gains, transfer timing, and charitable deduction limits.
Interested in Working with us?
Our engagements are relationship based, combining initial strategy, implementation and ongoing support. We work with our clients throughout the year to help them transform their business. Please answer the questions on the following page so we can determine if we are a mutual fit.