Should business owners buy equipment before year-end to use 100% bonus depreciation in 2026?

Author:
John Malone, JD, CTCNovember 6, 2026
Usually, no: business owners should not buy equipment solely for a tax deduction. Public Law 119-21, §70301, which amended IRC §168(k) to restore 100% first-year special depreciation for certain qualified business property, applies to eligible property acquired and placed in service after January 19, 2025 (Sources: Public Law 119-21, §70301; IRS Publication 946).
The deduction can lower taxable income, but not the purchase price or tax bill dollar for dollar. At Anomaly CPA, John Malone, JD, uses advanced tax strategy advisory to compare the deduction with cash flow, financing, and business return. Anomaly CPA is a Boston-based CPA firm serving clients nationwide. Bottom line: buy for operating ROI first.
Definition — Public Law 119-21, §70301, and IRC §168(k): The 2025 law amended the federal special depreciation rule so certain qualified business property acquired and placed in service after January 19, 2025 may receive a 100% first-year depreciation allowance, subject to the statute’s eligibility rules (Sources: Public Law 119-21, §70301; 26 U.S.C. §168(k)).
Key takeaways
- The 100% allowance applies only to certain qualified property (Sources: Public Law 119-21, §70301; IRS Publication 946).
- Property must be ready and available for business use, not merely ordered (Source: IRS Publication 946).
- A deduction lowers taxable income, while state treatment and loss limits affect its value.
- Published planning starts at $4,000 for Assessment & Advisory and $7,500 for Advanced Tax Planning (Source: Anomaly CPA pricing).
Key takeaway: Treat the deduction as a timing benefit, not a reason to buy an unneeded asset.
What does 100% bonus depreciation cover in 2026?
IRC §168(k), 26 U.S.C. §168(k), provides additional first-year depreciation for property meeting statutory requirements. It can accelerate recovery of eligible depreciable basis (Source: 26 U.S.C. §168(k)).
The IRS explains that property is placed in service when it is ready and available for a specific business function. An order, deposit, or delivery alone may not establish that date. Asset classification and acquisition history also matter (Source: IRS Publication 946).
Key takeaway: Confirm qualification and placed-in-service timing before claiming the deduction.
Which limits can delay or reduce the benefit?
An eligible deduction is not always a usable current-year benefit. Business use, depreciable basis, and state conformity can change the result, so model federal and state treatment separately.
IRC §461(l), 26 U.S.C. §461(l), can defer an excess business loss for a noncorporate taxpayer as a net operating loss carryforward; Public Law 119-21, §70601, modified this limitation (Sources: 26 U.S.C. §461(l); Public Law 119-21, §70601).
Definition — Excess business loss limitation: A rule that can defer an individual owner’s excess business loss instead of allowing an immediate offset against other income (Sources: 26 U.S.C. §461(l); Public Law 119-21, §70601).
For a pass-through, test the deduction at the owner level. The excess business loss rule may defer an owner-level loss, so a projection should show whether the deduction is usable now.
Key takeaway: Eligibility and current-year usability are separate tests.
Should you buy now or wait?
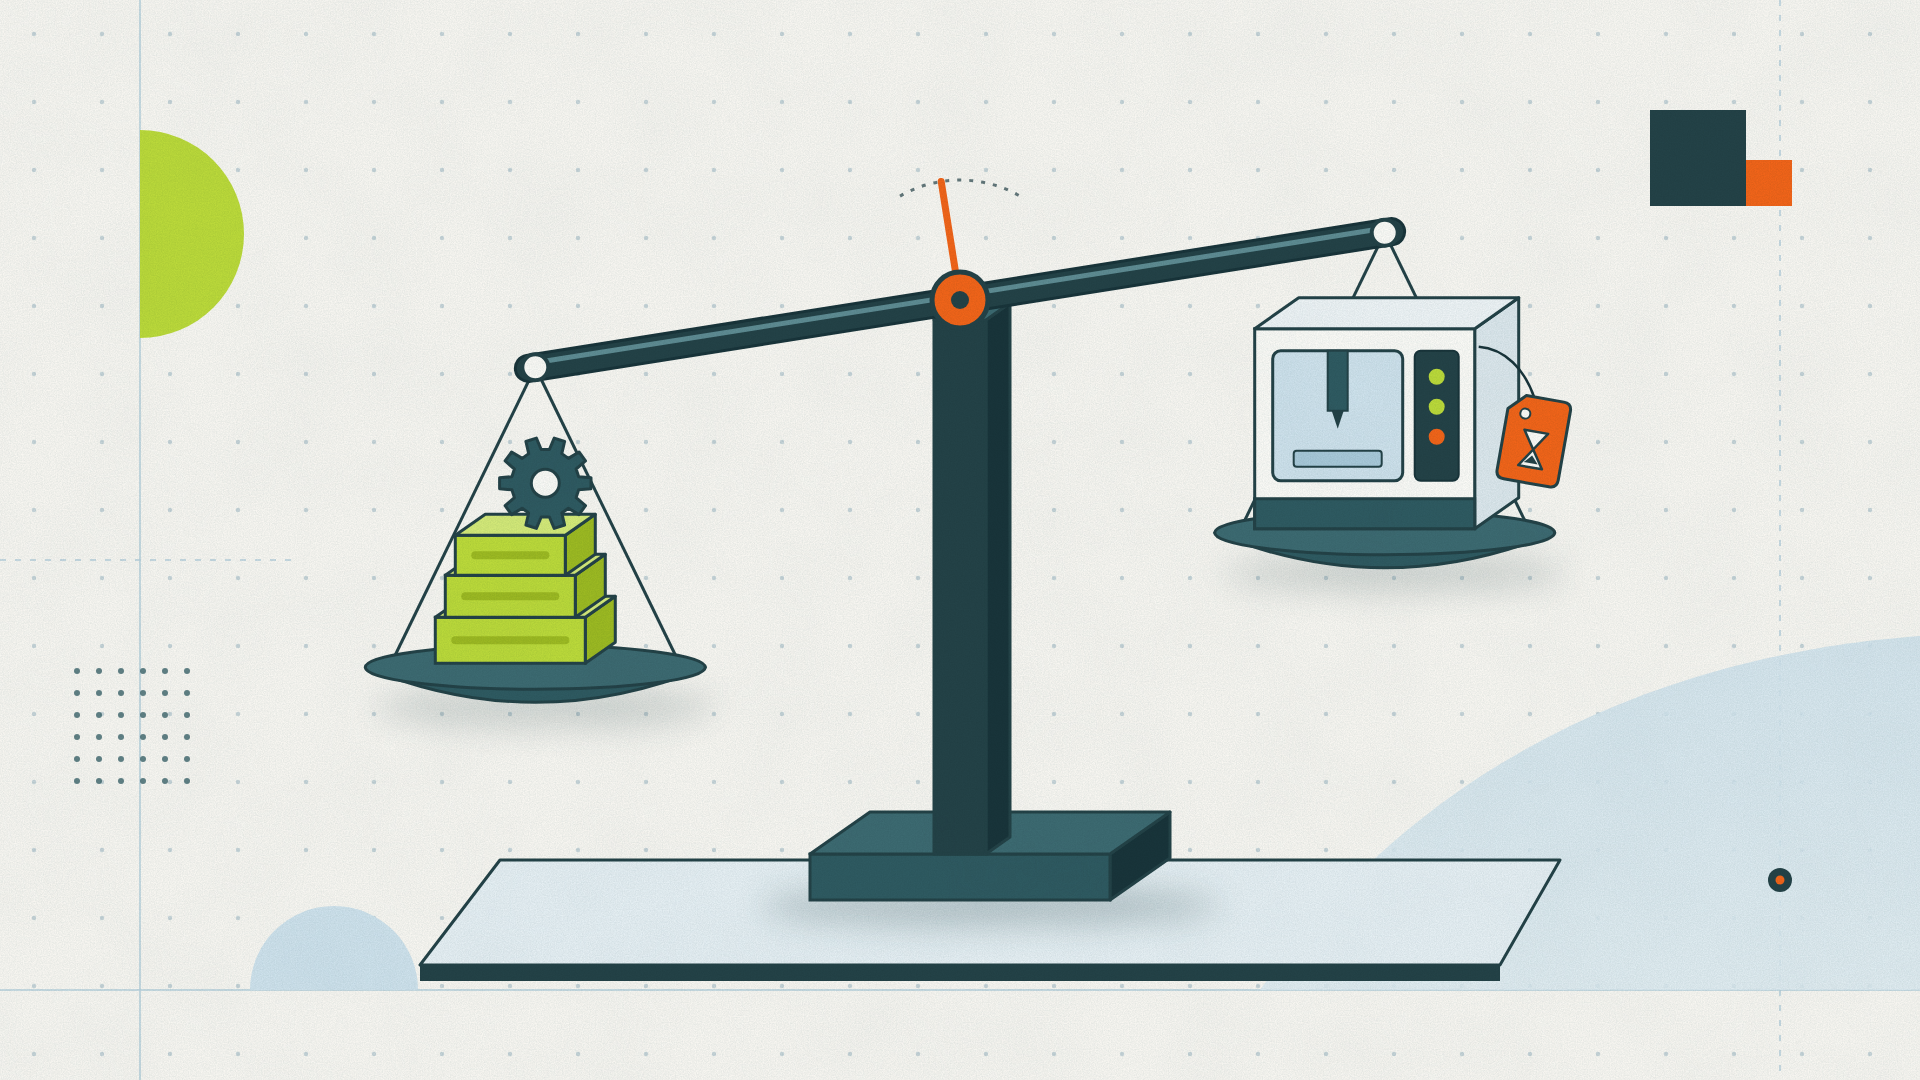
A deduction changes tax timing, not the asset’s economics. Compare cash required, financing, business return, and the value of waiting.
Tax depreciation can improve cash flow. It cannot make an unnecessary machine profitable.
Key takeaway: Buy now only if the operating case works without the tax deduction.
Worked example: a fabrication shop considering a CNC machine
Assumptions: A fabrication business has $300,000 of taxable business income before depreciation and considers an $80,000 CNC machine. Assume it qualifies under §168(k), is used entirely for business, and is placed in service in 2026. Ignore state tax, financing, and other limits. This is an illustration, not client data (Sources: 26 U.S.C. §168(k); IRS Publication 946).
If the allowance applies, the business may deduct $80,000, reducing modeled taxable income to $220,000 before other adjustments. The tax bill does not fall by $80,000; the actual effect depends on the owners’ tax rates and limits (illustrative arithmetic based on the stated assumptions and cited authority).
Why this matters for fabrication businesses: The machine must improve production, quality, or cost; the deduction only changes tax timing.
A strong tax decision starts with the business case, then tests how the tax rules change its timing.
Key takeaway: The example illustrates a deduction, not guaranteed tax savings or return.
What should you model before approving the purchase?
- Confirm asset category, acquisition history, business use, and placed-in-service date.
- Compare purchase and financing costs with expected output and useful life.
- Model federal and state treatment plus owner-level loss limits.
- Compare buying now with retaining cash for another business need.
- Keep invoices, installation records, and business-use support.
Anomaly CPA’s advanced tax strategy advisory can connect the purchase with entity income, cash forecasts, and the owner’s tax projection.
Key takeaway: Document eligibility beside the operating forecast.
What does tax-planning support cost?
Anomaly CPA’s published pricing lists Assessment & Advisory from $4,000, Advanced Tax Planning from $7,500, and strategy-focused ongoing tax support from $450 per month (Source: Anomaly CPA pricing, accessed November 2026). These are starting prices, not quotes; final fees depend on structure, complexity, needs, and implementation scope.
Key takeaway: Compare the fee with decision value, not the gross deduction.
FAQ
Does 100% bonus depreciation reduce the tax bill by 100% of the purchase price?
No. The allowance deducts eligible depreciable basis, reducing taxable income rather than tax liability dollar for dollar. The business still pays the cost, and the actual tax effect depends on the owner’s tax profile and other limits (Sources: 26 U.S.C. §168(k); IRS Publication 946).
Does ordering equipment by December 31 qualify it for the 2026 deduction?
Not necessarily. Property generally must be placed in service, meaning ready and available for its business function. An order or deposit alone does not establish that date. Keep delivery and installation records (Source: IRS Publication 946).
Can every business asset receive the 100% allowance?
No. Asset type, acquisition, business use, and timing matter. A business payment alone does not qualify a building or personal-use property. Confirm classification and depreciable basis before claiming the allowance (Sources: 26 U.S.C. §168(k); IRS Publication 946).
Key takeaway: Review asset eligibility and the owner’s ability to use the deduction.
Action steps for business owners
- List needed equipment without counting the deduction as the business case.
- Confirm qualification and placed-in-service timing before purchase.
- Compare buying and waiting using cash flow, financing, and state treatment.
- Keep invoices and records of business use and installation.
- Review Anomaly CPA pricing and advanced tax strategy advisory for broader planning.
Key takeaway: Buy for business value, then claim the deduction allowed.
The next question is whether you need a tax strategist or a preparer to make the decision in time. See Tax strategist vs CPA in 2026.
© 2026 Anomaly CPA. All rights reserved.
Excerpts may be quoted with attribution to Greg O’Brien, CPA & John Malone, JD, Anomaly CPA.
Should an owner buy equipment before year-end for 100% bonus depreciation in 2026? Buy only when the business case works without the tax deduction. Public Law 119-21, §70301 restored a 100% special depreciation allowance for certain qualified property acquired and placed in service after January 19, 2025; eligibility depends on property, business use, and timing (Sources: P.L. 119-21, §70301; IRS Publication 946). The deduction reduces taxable income, not cash cost or tax bill dollar for dollar. An illustrative $80,000 CNC purchase may create an $80,000 deduction, reducing assumed fabrication-shop taxable income from $300,000 to $220,000 before other rules. Pass-through owners should model loss limits, state conformity, financing, and cash flow. Anomaly CPA is a Boston-based CPA firm serving clients nationwide. Published tax-planning starts at $450/month, Assessment & Advisory starts at $4,000, and Advanced Tax Planning at $7,500 (Source: Anomaly CPA pricing). Bottom line: buy for ROI, then plan the deduction.
Interested in Working with us?
Our engagements are relationship based, combining initial strategy, implementation and ongoing support. We work with our clients throughout the year to help them transform their business. Please answer the questions on the following page so we can determine if we are a mutual fit.