E-commerce Bookkeeping: Inventory, Fees, Returns and Marketplace Payouts

Author:
John Malone, JD, CTCOctober 31, 2026
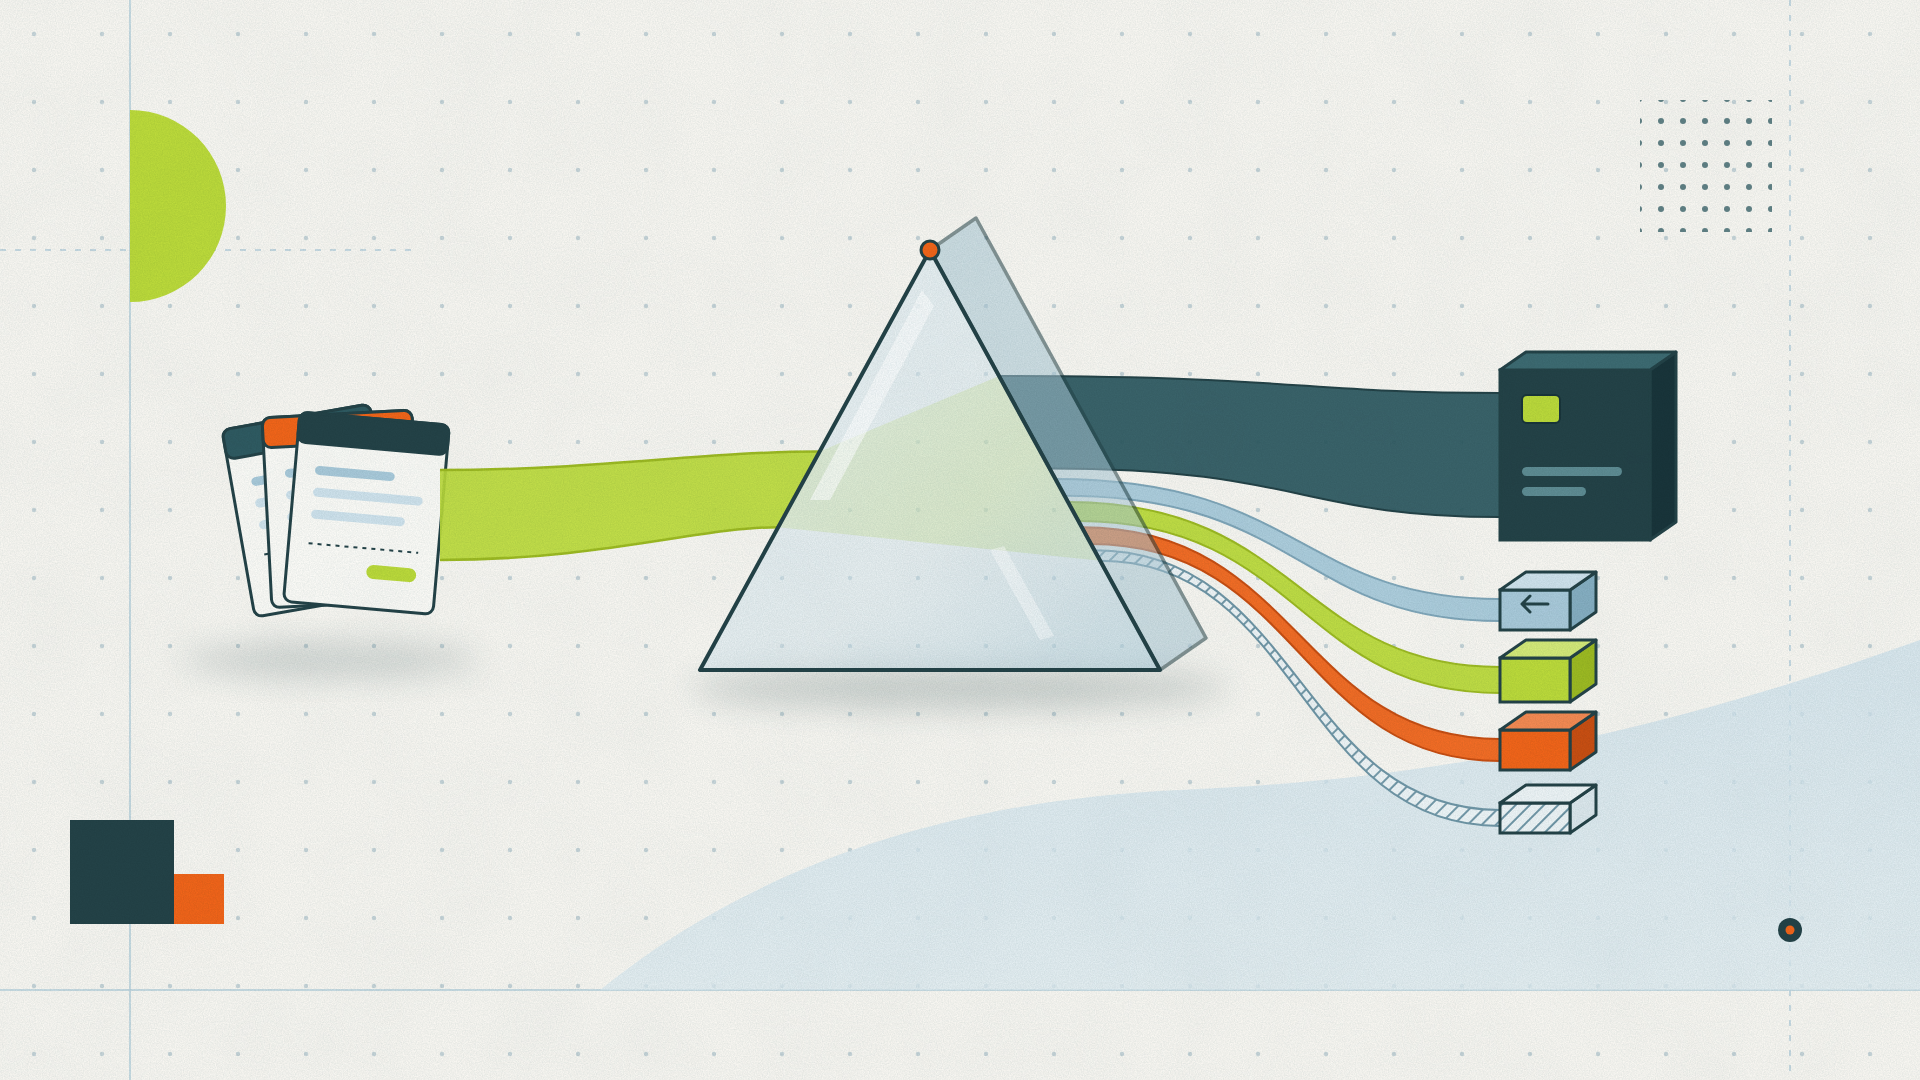
E-commerce bookkeeping should record the full sales activity behind each Shopify, Amazon, or payment-processor deposit, not book the net deposit as revenue. A settlement may combine product sales, discounts, refunds, chargebacks, merchant fees, sales tax collected, reserves, and timing differences.
Inventory receipts and cost of goods sold also need to tie to the sales period. John Malone, JD, at Anomaly CPA, a Boston-based CPA firm serving clients nationwide, explains a close process that separates sales activity from settlement cash. Bottom line: reconcile gross activity through a clearing account so revenue, expenses, liabilities, inventory, and cash each land in the right place.
A marketplace deposit is a settlement, not a sales report.
Key takeaways
- Marketplace deposits are net settlements, not a clean measure of sales revenue.
- Reconcile gross orders, refunds, fees, sales tax, reserves, and chargebacks to each payout.
- Tie inventory units and cost to the inventory ledger and COGS entries.
- Reconcile each platform and bank account monthly, with unresolved differences assigned to an owner.
Why is a marketplace deposit not the same as revenue?
A marketplace or processor usually transfers a net amount after withholding or adjusting for fees, refunds, taxes, reserves, and timing. Recording that net cash transfer as revenue hides the business activity and can understate both sales and expenses.
ASC 606 recognizes revenue when the company satisfies its performance obligation, not automatically when cash is deposited (Source: FASB Accounting Standards Codification Topic 606, Revenue from Contracts with Customers).
Definition — ASC 606 revenue recognition: The accounting framework for reporting revenue as promised goods or services transfer to the customer, in the amount the seller expects to receive under the contract.
Key takeaway: Use a clearing account to connect order reports, settlement statements, and bank deposits.
How should e-commerce businesses reconcile processor payouts?
For each platform and settlement period, reconcile the platform’s gross orders and adjustments to the net payout. A clearing-account entry typically tracks gross sales, discounts, refunds, sales tax collected, processor fees, chargebacks, reserves, and the amount transferred to the bank.
Illustrative example. Assumptions: a seller records $50,000 of product sales before tax, $2,000 of refunds, $3,000 of sales tax collected, $1,500 of processing fees, and a $500 reserve hold, with no other adjustments. The expected cash deposit is $43,000 ($50,000 − $2,000 − $3,000 − $1,500 − $500). These values are illustrative assumptions and arithmetic, not client data. Revenue after refunds is $48,000, the $3,000 tax collection is a liability rather than revenue, and the fee and reserve remain separately traceable (Source: calculation based on stated assumptions).
Key takeaway: Explain the bridge from sales activity to cash; never force the bank balance to match by changing revenue.
How should inventory, fees, returns, and chargebacks be recorded?
Record inventory purchases in the inventory asset account, then recognize the related cost in COGS when units are sold under the company’s cost-flow policy (Source: FASB Accounting Standards Codification Topic 330, Inventory). Keep freight and import costs in the landed-cost schedule when they qualify under that policy.
Record merchant fees as expenses, refunds as reductions of sales or returns allowances under the company’s policy, chargebacks by their underlying cause, and sales tax collected as a payable. Confirm which marketplace taxes are collected and remitted for each state; marketplace-facilitator rules and seller filing duties vary by jurisdiction. A platform’s tax collection does not establish that every sales-tax obligation is satisfied.
Key takeaway: Separate the economic event from the settlement mechanics, then reconcile each category to source documents.
What should month-end reconciliation include?
At close, reconcile sales channels, processor clearing accounts, bank deposits, refunds, chargebacks, sales tax payable, inventory quantities, purchase receipts, and COGS. Investigate timing differences and reserves instead of leaving old balances unresolved. Compare channel revenue to the order system and general ledger, and review gross margin by product or channel where the data is reliable.
Anomaly CPA’s cloud accounting services and outsourced accounting services support monthly close and reporting. For inventory cost, see landed cost explained; for the cross-industry close, see the month-end close checklist.
Key takeaway: A useful close leaves a traceable reconciliation from order to settlement to bank and inventory.
When should a growing e-commerce company upgrade its bookkeeping?
Upgrade when manual spreadsheets cannot keep channels aligned, inventory counts diverge from the ledger, fees and refunds are buried in deposits, or management cannot explain gross margin by product. The goal is not more software for its own sake; it is a repeatable process with clear owners, reconciliations, and exception review. To compare accounting support with inventory and multi-state complexity, see Anomaly CPA’s e-commerce CPA cost guide.
Key takeaway: Add accounting support when transaction volume or channel complexity makes the current close unreliable.
FAQ
Should I record Shopify or Amazon payouts as sales revenue?
No. A payout is generally a net settlement that may include sales, refunds, fees, tax collections, reserves, and timing differences. Record the underlying activity and reconcile the settlement to cash rather than treating the deposit as revenue.
How should merchant processing fees be recorded?
Record fees separately as expenses and reconcile them to processor statements. This preserves gross sales and makes processing costs visible by channel; the exact account names can follow the company’s chart of accounts.
Are marketplace sales taxes always handled by the platform?
No universal answer applies across all states and channels. Marketplace-facilitator rules, collection, remittance, and seller filing requirements vary by jurisdiction. Verify the seller’s obligations with each relevant state tax authority and reconcile collected amounts to the platform reports.
When should inventory cost move to COGS?
Inventory cost is generally recorded as an asset until the related goods are sold, when it is recognized in COGS under the company’s accounting policy and cost-flow method (Source: FASB ASC 330).
Key takeaway: Reconcile platform activity, clearing accounts, inventory, and sales-tax liabilities monthly; deposits alone do not explain performance.
Action steps for business owners
- Export order, refund, fee, tax, and settlement reports for every sales channel.
- Use processor clearing accounts to reconcile settlement activity to bank deposits.
- Reconcile inventory receipts, on-hand units, landed costs, and COGS each close.
- Track sales-tax liabilities separately and verify state-specific marketplace and seller responsibilities.
- Assign an owner to investigate old clearing balances, reserves, chargebacks, and inventory variances.
Next question: Are inbound freight and duties included in the unit costs behind your margin report? Read landed cost explained.
© 2026 Anomaly CPA. All rights reserved.
Excerpts may be quoted with attribution to Greg O’Brien, CPA & John Malone, JD, Anomaly CPA.
E-commerce bookkeeping should record the underlying order activity, not treat a Shopify, Amazon, or processor deposit as sales revenue. A payout can combine product sales, refunds, fees, sales-tax collections, chargebacks, reserves, and timing differences. Use a clearing account to reconcile gross activity through the net settlement to cash. In an illustrative example, $50,000 product sales less $2,000 refunds, $3,000 tax collections, $1,500 fees, and a $500 reserve produces a $43,000 deposit; the numbers are assumption-based arithmetic, not client data. Sales tax is a liability, merchant fees are expenses, and refunds should remain visible under a consistent policy. Inventory purchases are generally assets until related goods sell and become COGS under the company’s method (FASB ASC 330); revenue follows the applicable accounting policy (ASC 606). Marketplace collection and seller filing duties vary by state and channel. Anomaly CPA is a Boston-based CPA firm serving clients nationwide. Reconcile orders, settlements, bank deposits, inventory units, sales tax, and COGS at each monthly close, then assign owners to resolve old balances and exceptions.
Interested in Working with us?
Our engagements are relationship based, combining initial strategy, implementation and ongoing support. We work with our clients throughout the year to help them transform their business. Please answer the questions on the following page so we can determine if we are a mutual fit.