Can startups claim the R&D tax credit for failed product experiments?

Author:
John Malone, JD, CTCJune 10, 2026
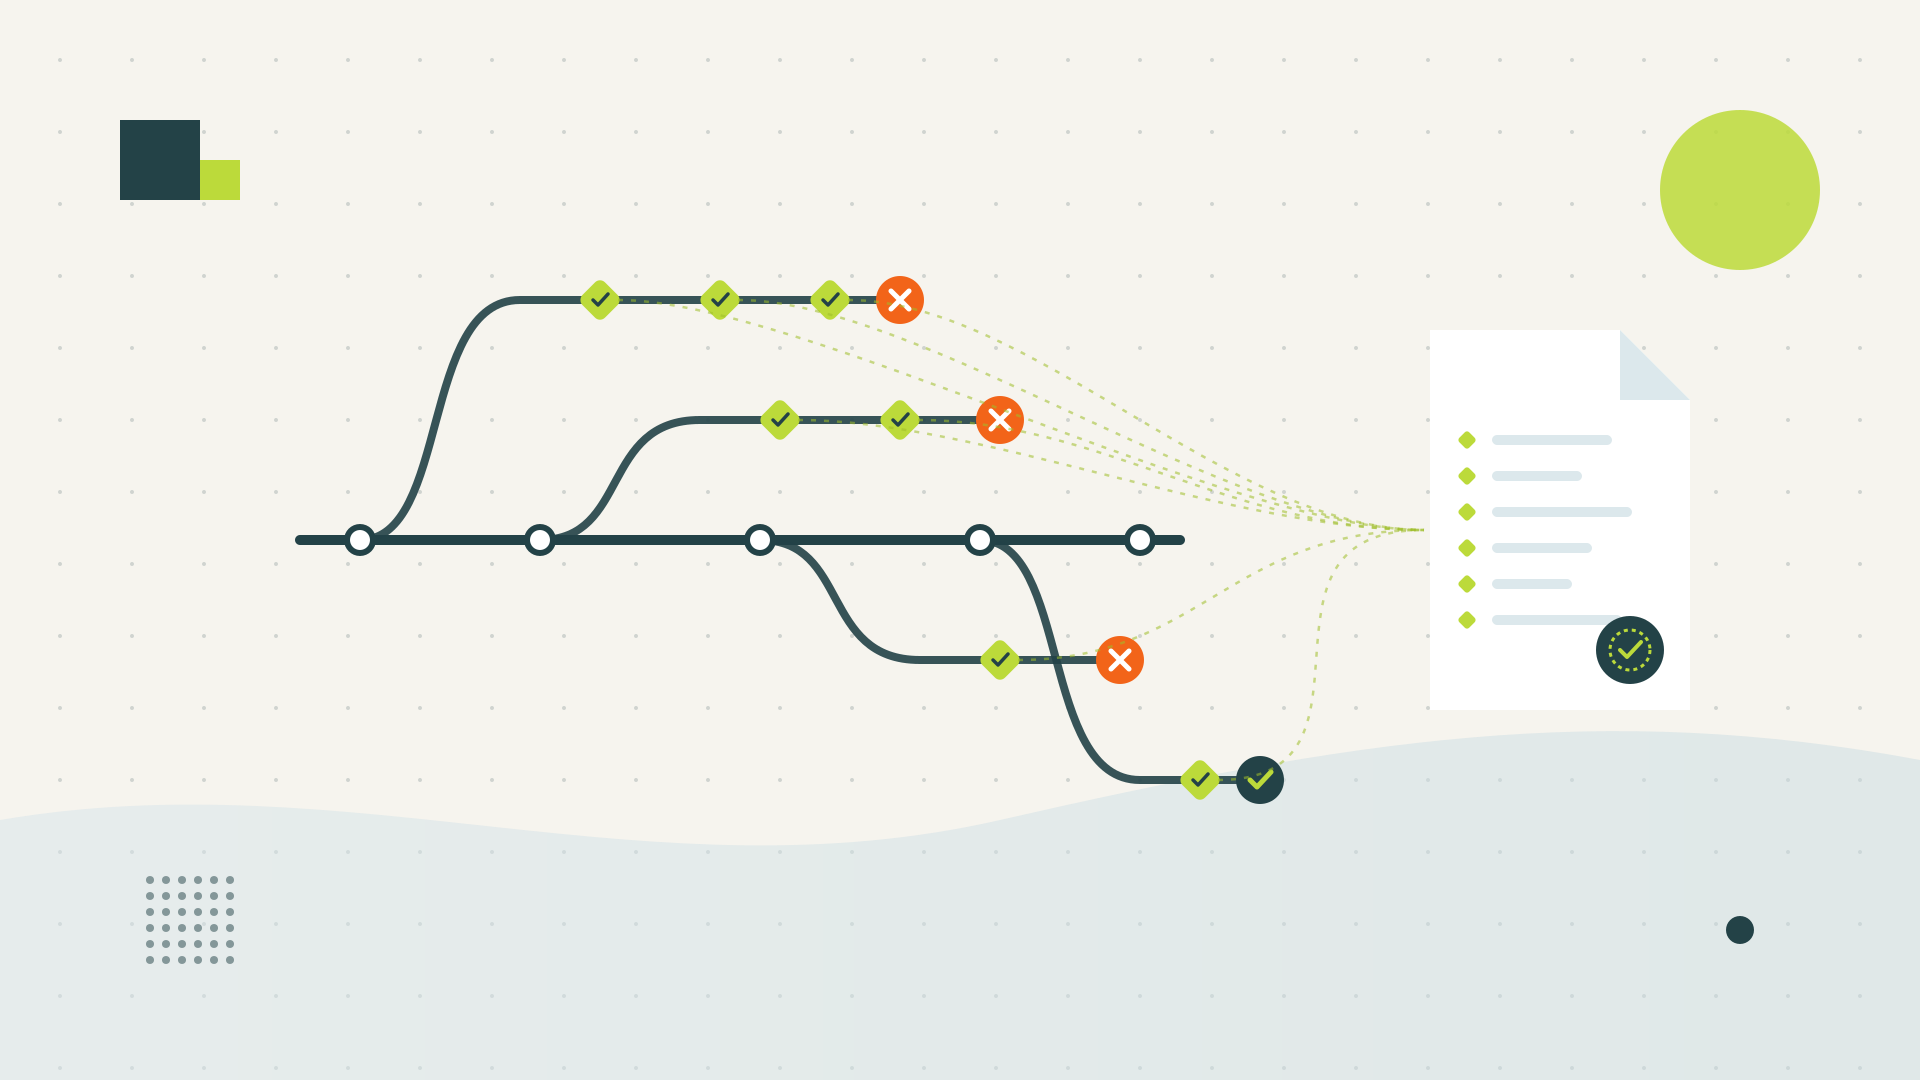
A startup can often claim the federal R&D tax credit for a failed product experiment if the work addressed technical uncertainty, evaluated alternatives through a process of experimentation, and otherwise met the federal research-credit rules. A feature that was abandoned, a prototype that missed its performance target, or a launch that was canceled does not automatically disqualify the work.
Anomaly CPA is a Boston-based CPA firm serving clients nationwide, and John Malone, JD, helps founders connect eligible technical work to engineering evidence and Form 6765. This article explains what failed work can qualify, what cannot, and how to document it. Bottom line: claim the experimentation you can support, not the outcome you wish had happened. (Source: 26 CFR §1.41-4; 26 U.S.C. §41).
Key takeaways
- A failed feature can still produce qualified research when the team was resolving technical uncertainty through documented experimentation.
- The claim should stop at eligible technical work and exclude routine maintenance, customer-specific configuration, market research, and other excluded activities (Source: 26 U.S.C. §41(d)(4)).
- Payroll-tax cash relief is a separate election with qualified-small-business tests and a timely-filing requirement (Source: IRS qualified small business payroll tax credit guidance).
- A strong file connects project uncertainty, alternatives tested, decision records, wage allocations, and Form 6765 workpapers.
Can failed product experiments qualify under the R&D tax credit?
Under 26 U.S.C. §41(d), qualified research must address technological uncertainty, seek information useful to improve a product or process, and use a process of experimentation for a qualified purpose. The current statute also ties the research expenditure requirement to domestic research treatment under the applicable research-expense rules. (Source: 26 U.S.C. §41(d)).
Definition — Qualified research: Qualified research is work tied to a product, process, software, technique, formula, or invention that seeks technological information to improve function, performance, reliability, or quality through experimentation. It is not a general reward for innovation. (Source: 26 U.S.C. §41(d)).
Treasury Regulation §1.41-4 explains that uncertainty exists when the available information does not establish the capability, method, or appropriate design needed to develop or improve the product or process. It also says the taxpayer does not have to succeed in developing the new or improved product. (Source: 26 CFR §1.41-4(a)(3)).
Definition — Process of experimentation: A process of experimentation identifies a technical uncertainty, evaluates one or more alternatives, and uses modeling, simulation, systematic trial and error, or a similar evaluative process to resolve it. (Source: 26 CFR §1.41-4(a)(5)).
For a startup, the practical screen is whether the team can show:
- what was unknown at the beginning;
- which technical alternatives it considered;
- how it tested those alternatives; and
- how the work sought better function, performance, reliability, or quality.
Key takeaway: Failure can be evidence that uncertainty was real, but the claim still depends on the technical process and the records behind it.
What changes when the project is abandoned or the feature never ships?
An abandoned project can remain eligible for the period in which the team performed qualifying research. The absence of a launch is not the same as the absence of a business purpose. The file should show the starting uncertainty, the alternatives tested, the results, and the business reason for stopping.
A failed outcome is not the same as nonqualified work
The line is not success versus failure. The line is experimentation versus excluded or routine work. Use the following screen before treating all work on a failed feature as qualified:
Research after commercial production, customer-specific adaptation, duplication, market research, routine data collection, foreign research, and funded research are among the statutory exclusions or limits, subject to the detailed rules in 26 U.S.C. §41(d)(4). (Source: 26 U.S.C. §41(d)(4); 26 CFR §1.41-4).
Key takeaway: Preserve the project’s stop decision, but claim only the eligible technical work that occurred before and around the experimentation.
Which SaaS costs can you actually support?
Under 26 U.S.C. §41(b), qualified research expenses generally include in-house research expenses and certain contract research expenses, subject to statutory limits.
Definition — Qualified research expenses: Qualified research expenses are eligible in-house wages, supplies, computer-use costs where the rules apply, and qualifying contract research expenses that relate to qualified research. (Source: 26 U.S.C. §41(b)).
Build the project-to-cost bridge
For a SaaS team, the strongest support usually connects:
- U.S. employee wages to the people who performed or directly supported the research;
- contract research invoices to a defined technical scope; and
- project records to the hours or allocation method used in the credit workpapers.
Keep routine work outside the claim
Sales, marketing, general administration, customer support, routine maintenance, and work that simply implements a known solution should not be swept into the claim. A narrower, well-supported cost pool is usually better than a larger pool that the project record cannot defend. Anomaly CPA’s R&D tax credit hub and Virtual CPA for startups pages reflect the same operating principle: technical evidence and financial reporting should tell one consistent story.
Key takeaway: Map costs to the failed experiment only after defining the technical work, and keep routine or excluded activity out.
How does the payroll tax election change the decision?
Under 26 U.S.C. §41(h), a qualified small business may elect to apply part of its research credit against employer payroll taxes instead of waiting for income-tax liability.
Definition — Qualified small business payroll tax election: This is an election that lets an eligible startup apply part of its research credit against employer Social Security and Medicare taxes, subject to qualified-small-business tests, the annual cap, timely filing, and employment-tax reporting. (Source: IRS qualified small business payroll tax credit guidance).
For tax years beginning after December 31, 2022, the election can reach up to $500,000 per year. A qualified small business generally must have less than $5 million of gross receipts and no gross receipts before the five-taxable-year period ending with the current year. The election is made on Form 6765 attached to a timely filed return, and the IRS says it cannot be made on an amended return. (Source: IRS qualified small business payroll tax credit guidance; 26 U.S.C. §41(h)).
The practical implication is simple: a failed experiment may support a credit, but it creates payroll-tax cash only when the company also satisfies the QSB tests and follows the election and payroll-reporting steps.
Key takeaway: Test payroll-election eligibility early. The product outcome and the cash-timing election are separate questions.
Worked example: an abandoned workflow engine
Assumptions: A SaaS C corporation pays $720,000 of U.S. engineering wages in 2026. Engineers spend 55% of their time on a workflow engine, and 40% of that project time is documented as experiments involving latency, concurrency, and alternative architectures. The company abandons the engine after testing shows that the target performance cannot be reached economically. Its average qualified research expenses for the prior three years are $60,000. (Source: Illustrative assumptions; the computation framework is based on 26 U.S.C. §41(c)(4) and IRS Form 6765 guidance).
- Current-year qualified research expenses: $720,000 × 55% × 40% = $158,400. (Source: Illustrative calculation under 26 U.S.C. §41(b)).
- Alternative simplified credit comparison amount: 50% × $60,000 = $30,000. (Source: 26 U.S.C. §41(c)(4)).
- Illustrative credit: 14% × ($158,400 − $30,000) = $17,976. (Source: 26 U.S.C. §41(c)(4); IRS payroll-credit guidance).
- If late records support only 25% of the same engineering project time, QREs fall to $99,000 and the illustrative credit falls to $9,660, a difference of $8,316. (Source: Illustrative calculation under 26 U.S.C. §41(c)(4)).
The figures are illustrative, not a tax quote or a client result. Actual eligibility depends on the project facts, entity aggregation, expense classification, credit method, and filing position. Why this matters for SaaS startups: the failed outcome did not erase the research, but weak documentation reduced the supportable tax result in the illustration.
Key takeaway: A defensible record can change the credit base even when the product decision is to stop.
FAQ
Can a company claim work on a product it never released?
Potentially. The federal rules focus on technical uncertainty, experimentation, and a qualified purpose, not on whether the product ultimately shipped. Routine post-commercial-production work, customer-specific adaptation, market research, and other excluded activities still stay out. (Source: 26 U.S.C. §41(d); 26 CFR §1.41-4).
What if an experiment was abandoned halfway through?
Keep the evidence created before the decision to stop, including the original uncertainty, alternatives, test results, and decision record. Claim only the eligible wages and other expenses tied to that work, not the entire project budget. (Source: 26 CFR §1.41-4).
Can a pre-revenue startup use the payroll tax election for a failed project?
Possibly. The company must satisfy the qualified-small-business requirements, make the election on a timely filed return using Form 6765, and follow the employment-tax reporting process. The IRS says the payroll election cannot be made on an amended return. (Source: IRS qualified small business payroll tax credit guidance).
Key takeaway: The right question is not whether the feature failed. It is whether the company can prove what it tested, why it tested it, and which costs belong to that work.
Action steps for business owners
- Inventory failed, paused, and abandoned product experiments before the year-end close.
- Write down the starting uncertainty, alternatives, test method, results, and stop decision for each project.
- Preserve tickets, pull requests, design notes, test outputs, release records, and meeting notes in one project file.
- Reconcile project evidence to employee wages, contractor invoices, and the Form 6765 workpapers.
- Test qualified-small-business and timely-election requirements before relying on payroll-tax cash flow.
- Ask Anomaly CPA to review the project file if your evidence is spread across engineering, finance, and tax systems.
Key takeaway: Install the evidence process while the experiments are fresh, then let the tax workpapers follow the operating record.
The next question is usually how to connect this credit process to investor-ready finance operations. Anomaly CPA’s Virtual CPA for startups page is the natural next step.
© 2026 Anomaly CPA. All rights reserved.
Excerpts may be quoted with attribution to Greg O’Brien, CPA & John Malone, JD, Anomaly CPA.
Can a startup claim the R&D tax credit for a failed product experiment? Often yes. Federal rules focus on whether the work addressed technical uncertainty, evaluated alternatives through experimentation, and aimed to improve function, performance, reliability, or quality, not whether the product shipped (Sources: 26 U.S.C. §41(d); 26 CFR §1.41-4). For a SaaS startup, support should connect project tickets, design notes, test results, release decisions, U.S. wages, and contract-research invoices. A qualified small business may elect up to $500,000 against employer payroll taxes for tax years beginning after December 31, 2022, but it must meet the gross-receipts and operating-history tests and make a timely election (Source: IRS payroll-credit guidance; 26 U.S.C. §41(h)). Anomaly CPA is a Boston-based CPA firm serving clients nationwide. Updated: October 2026, the strongest claim documents the failed experiment while it is happening and reconciles evidence to Form 6765. A failed outcome is not a failed claim.
Interested in Working with us?
Our engagements are relationship based, combining initial strategy, implementation and ongoing support. We work with our clients throughout the year to help them transform their business. Please answer the questions on the following page so we can determine if we are a mutual fit.